AppLovin Corporation
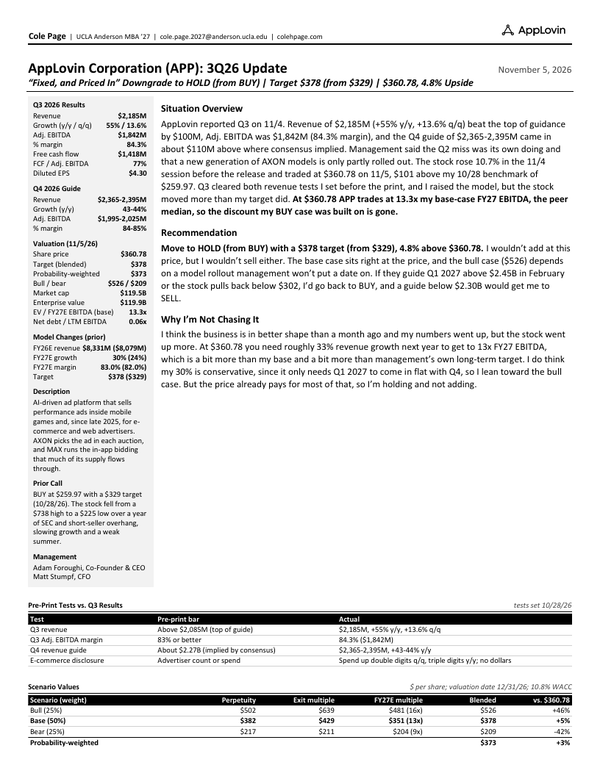
AI ad platform at 13.3x my FY27 EBITDA after a beat-and-raise Q3. The discount to peers my BUY case rested on is gone, and the bull and bear cases are now about the same size.
- Sector
- Advertising Technology
- View
- Market Weight
- Ratings
- NR / NR
- Class
- Equity
- Updated
- 05-Nov-26
Current View
AppLovin runs an AI ad platform that sells performance ads inside mobile games and, since late 2025, for e-commerce and web advertisers. AXON picks the ad in each auction, and much of the supply it bids on runs through MAX, AppLovin's own in-app bidding and mediation product, so in gaming it sits on both sides of the auction. FY25 revenue was $5,481M (+70%) at an 82% Adjusted EBITDA margin, and free cash flow was 88% of EBITDA. The open question is whether e-commerce, open to all advertisers since June 2026, can take over from gaming as the growth engine. The company still doesn't report it separately.
I rated it BUY at $259.97 on 10/28 with a $329 target, after a year-long fall from $738 left it at 10.5x FY27 EBITDA against a 13.3x peer median (the memo). Q3 cleared both revenue tests I set, and the stock traded at $360.78 on 11/5.
HOLD, $378 target. At $360.78 APP trades at 13.3x my base-case FY27 EBITDA, the peer median, and the bull (+46%) and bear (-42%) cases are about the same size. I'd go back to BUY on a Q1 2027 guide above $2.45B or a price below $302, and to SELL on a guide below $2.30B. The 3Q26 update has the scorecard, the model changes and the triggers.
Research
AppLovin 3Q26: Downgrade to HOLD After the Beat
Update· PDFQ3 cleared every test I set on 10/28 and I raised the target to $378, but the stock got to $360.78, 13.3x my FY27 EBITDA and the peer median. The bull and bear cases are now about the same size.
EquityAppLovin: BUY at $260 Ahead of the First Full E-commerce Quarter
Equity Memo· PDF· Updated 05-Nov-26BUY at $259.97 with a $329 target. An SEC inquiry, short reports, four quarters of slowing growth and a weak summer have taken the stock from $738 to 10.5x FY27 EBITDA against a 13.3x peer median, and my base case only needs consensus numbers.
Equity